Housing Counselor, Lender or Agent: Who Can Help You?
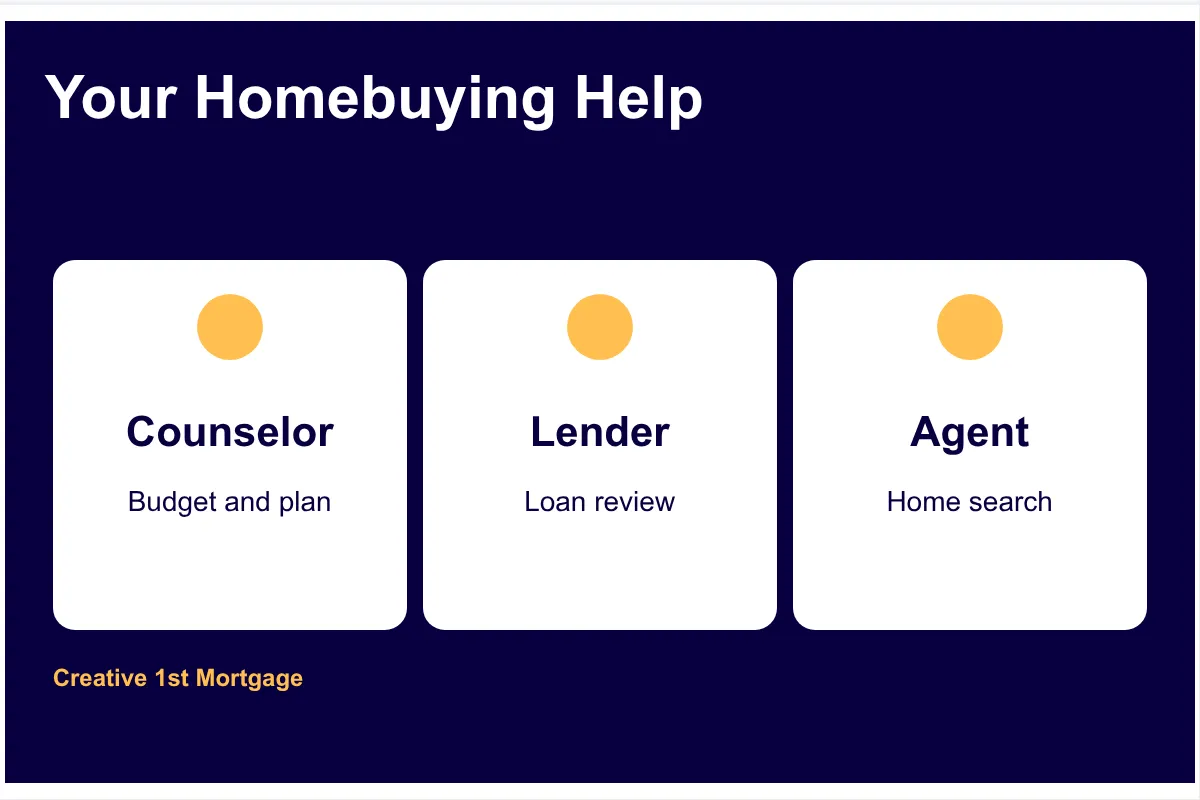
If you need help sorting out your budget and next steps, start with one-on-one housing counseling. If you need a loan review, talk with a lender. If you are ready to search for homes or make an offer, an agent can help. These roles can overlap, but each has a different main purpose.
You do not need to rely on one person for every homebuying question. The Consumer Financial Protection Bureau encourages buyers to build a network of trusted advisers and seek other views for major decisions. Its homebuying adviser guidance includes pre-purchase counseling as one option.
For a wider look at the process, see this first-time home buyer mortgage guide. This article focuses on deciding who to contact for the question in front of you.
When a counselor may be the best first call
A Housing Counselor may be useful when your concern is personal planning, not just general information. You may have attended a class or read online guides but still feel unsure about your own budget, priorities, or barriers.
The U.S. Department of Housing and Urban Development, often called HUD, says participating agencies provide advice tailored to the client. Pre-purchase counseling may include a personal financial and affordability review, an action plan, and follow-up when possible. Review HUD’s housing counseling information and search tool to find participating agencies.
Consider asking for individual counseling when you want help with questions like these:
- What parts of my finances need more attention?
- What homeownership costs should I plan for?
- What steps belong in my action plan?
- What should I work on before moving forward?
A counselor can help you turn broad concerns into a plan. That does not make counseling a loan approval or a promise of a credit result. It is planning support.
A workshop and counseling are not the same
A group or online workshop gives general education. Individual counseling is tailored to your situation. Both can be useful, but a workshop may not answer questions about your own finances or priorities.
Do not assume a class meets a requirement for a loan or another program. Ask the relevant program office whether it accepts a particular workshop or counseling service. Also ask the agency what it offers before you schedule.
Services vary by agency. Some agencies may offer phone or online sessions. HUD says some counseling or workshops may charge reasonable fees that are disclosed in advance. HUD also says agencies must waive fees that clients cannot afford. Ask about services and fees directly.
Match the question to the right professional
A counselor, lender, and agent may all provide helpful information. Still, using the right person first can save time and make your next step clearer.
| Question you have | Helpful starting point | Main focus |
|---|---|---|
| How can I make a personal plan? | Housing counselor | Budget and action plan |
| How might a loan be reviewed? | Lender | Qualification, options, and papers |
| How do I find homes or prepare an offer? | Agent | Home search and offer help |
Freddie Mac explains that a counselor can help assess finances, plan a budget, and prepare for ownership. It also notes that a lender reviews loan qualification, explains loan options, costs, and terms, and identifies needed documents. An agent can help find a home, prepare an offer, and negotiate with the seller. Read its overview of who is on a homebuying team for more context.
Use a lender for loan-specific questions
Talk with a lender when your question is about a mortgage review. A lender can discuss how loan qualification is reviewed, what documents may be needed, and how loan options, costs, and terms work.
Bring clear questions. For example, ask what information the lender needs to review your situation and what parts of the loan process need your attention. A counselor may help you prepare for this conversation, but counseling does not replace a lender’s loan review.
Use an agent for the home search
Talk with an agent when you want help finding a property, preparing an offer, or negotiating with a seller. An agent’s role becomes especially useful when your questions focus on homes rather than on your personal budget or loan review.
Property choices can affect your plans. Share relevant concerns early with the professionals helping you. Then each person can address the part that fits their role.
Build a small support team
You may not need all three professionals at once. Start with the question that is holding you back. If you need a personal plan, seek counseling. If you need loan-specific information, contact a lender. If you are ready to search and make offers, speak with an agent.
This is educational information, not loan approval, program acceptance, or a promise of funding. Requirements, services, fees, and availability can change. Confirm current details with the counseling agency, lender, agent, or program office involved.
Before your next call, write down three things: the decision you need to make, the facts you already know, and the questions you still have. Ask a counseling agency whether it provides individual pre-purchase counseling, how sessions are offered, and whether fees apply. Ask a lender which questions require a loan review. Ask an agent how they can help with your home search and offer process.