Pinellas County Down Payment Assistance: Who Does What
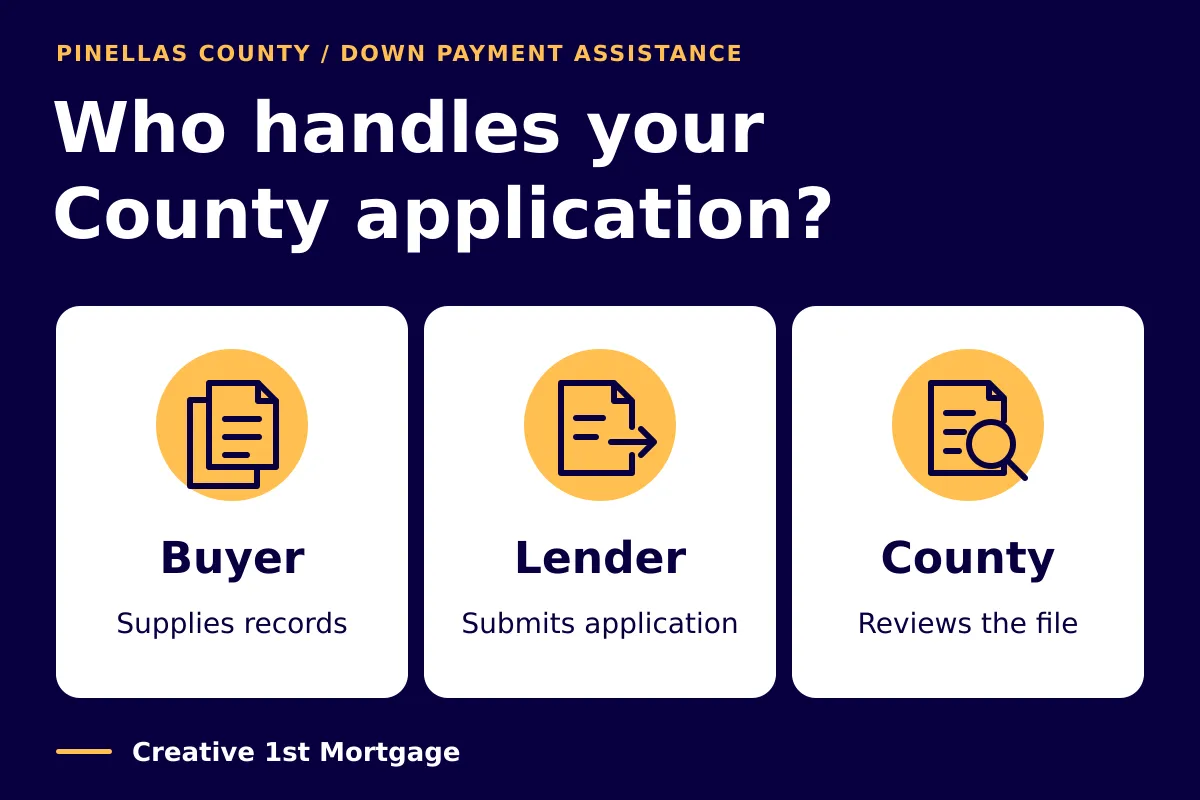
Your first-mortgage lender submits a Pinellas County down payment assistance application. Your part is to supply the records, take the required class and counseling, and answer requests for missing items. The County checks the file and uses a contractor for its required home inspection.
The useful question is not just “Is my file moving?” Ask which step is next, who owns it, and what that person needs from you. Sending papers to your lender is not the same as the lender sending your application to the County.
Make sure this is the right County route
This guide is for the County program in its eligible service area. St. Petersburg, Clearwater, and Largo have their own city programs. Housing Finance Authority programs are separate, too. A home’s Pinellas County mailing address does not tell you which route to use.
Ask the lender or program staff to check the property address first. If you have not chosen a program, start with the local first-time homebuyer program guide. This page focuses on who does what after you have chosen the County route.
Who does what in the County application?
Step | Who handles it | What to ask |
|---|---|---|
Check the address and route | Buyer, lender, and program staff | Is this home in the County service area? |
Supply records | Buyer | Which items are still missing? |
Finish the class and counseling | Buyer | Which course and counselor does the program accept? |
Submit the application | First-mortgage lender | Was it sent, or is it still being prepared? |
Check the file against program rules | County Community Development | Does the County need more information? |
Required property standards inspection | County uses a third-party contractor | Who will explain any next steps? |
Your job: supply records and check what is missing
The County file may need records beyond those used for your mortgage. The County-linked underwriting guide describes proof of who lives in the home, income, and assets. It is a guide to the kinds of records the County may need, not a promise that an older checklist covers every current request.
Ask your lender for a clear list of missing items. For each one, ask whether it is for the mortgage, the County file, or both. Send accurate records and keep copies. If you do not know what a request means, ask before you send the wrong item.
You also need to finish the required homebuyer class and individual counseling before closing. Use HUD’s housing counseling locator to find agencies to contact. Before you book, ask the County or lender which course and counseling will be accepted. A listing alone does not prove that a course meets the program’s current rules.
The lender’s job: submit the County file
The County program page says the first-mortgage lender must submit the application. Giving your lender records or filling out a mortgage application does not prove this step is done.
The County-linked lender guide shows that a file can be saved before it is completed and sent. The guide has no clear revision date, so do not rely on its screenshots as a guide to the current portal. The key point is to confirm that the lender has submitted the file, not just saved it.
Ask: “Has my County application been sent?” If not, ask what is missing and who must supply it. If it has been sent, ask who will tell you when the County needs more information. These questions help make the next step clear without assuming a review date or an approval.
The County’s job: review the file and use its inspection process
County Community Development checks the application package against the program’s rules. The County also uses a third-party contractor for the required property standards inspection.
Do not treat that inspection as the same as your own home inspection or the lender’s appraisal. Ask which review a request comes from. If an issue is raised, ask who must act next and what the County needs to see. Do not assume that a result from one review settles a question in another.
Questions to ask before the next handoff
What is the next step, and who is handling it?
What do they need from me or someone else?
How will I know that step is complete?
This is educational guidance, not an approval or a claim that funds are available. Check current rules, accepted courses, address eligibility, and program availability with the County and your lender. For the wider purchase process, see the first-time home buyer mortgage guide.